Quick Answer: What records should I keep for FBR?
Pakistani businesses, freelancers, and professionals should maintain organized records of filed income-tax returns, bank statements, invoices, contracts, and withholding tax evidence. FBR guidance states that persons with taxable income should keep income-tax return records for six years. Sales-tax registered persons must also retain relevant records for six years after the end of the tax period.
A tax return is only as reliable as the records behind it. For a business owner, freelancer or professional in Pakistan, organized records help support income, expenses, assets, liabilities and tax deducted at source. They also make it easier to prepare a return, reconcile a Wealth Statement, answer an FBR query and understand the financial position of the business.
Record keeping is not only an accounting best practice. FBR guidance says persons with taxable income should keep income-tax return records for six years. The Income Tax Ordinance, 2001 and applicable rules should be checked for the precise obligation in a taxpayer’s circumstances. If you need to get your initial registration sorted, read our guide on NTN Registration in Pakistan.
What Is Tax Record Keeping?
- Tax Record Keeping Definition:
- Tax record keeping means maintaining organized, accurate evidence of transactions and financial information used to prepare tax returns and meet legal obligations. It includes source documents—such as invoices and bank statements—as well as accounting records that summarize those documents.
How Long Should You Keep Tax Records in Pakistan?
FBR’s income-tax filing guidance states that persons with taxable income should keep income-tax return records for six years. FBR’s sales-tax records guidance also states that registered persons must retain relevant records and documents for six years after the end of the tax period to which they relate. Where a proceeding, special rule or other legal requirement affects retention, obtain advice before disposing of records. A safe operational approach is to maintain an organized digital archive and not destroy documents connected to an unresolved FBR matter. If you receive a notice, read our guide on how to respond to an FBR tax notice.
1. Records Every Taxpayer Should Organize
- Copies of filed income-tax returns and Wealth Statements, with submission acknowledgements.
- IRIS notices, responses, receipts and relevant FBR correspondence.
- Bank statements and evidence of significant receipts or payments.
- Evidence of tax deducted or collected at source, including certificates and transaction records where available.
- Documents supporting assets, liabilities, investments and material changes in net worth.
- Records supporting tax credits, adjustments, exemptions or refund claims made.
Understanding your status is key; read about the Active Taxpayer List (ATL) in Pakistan to know your standing.
2. Additional Records for Businesses
- Sales invoices, receipts, credit notes and debit notes.
- Purchase invoices and supplier records.
- Contracts, purchase orders and customer agreements.
- Expense vouchers, utility bills, rent agreements, payroll and other operating-cost evidence.
- Cash book, bank book, general ledger and trial balance.
- Inventory movement and stock-count records where relevant.
- Fixed-asset register, purchase/disposal evidence and depreciation workings where relevant.
- Loan agreements, repayment schedules and evidence of capital introduced or withdrawn.
- Withholding-tax calculations, statements, deposit evidence and reconciliation records where the business acts as a withholding agent.
For a broader understanding of business obligations, read about how to register a business for tax in Pakistan and Withholding Tax in Pakistan.
3. Additional Records for Freelancers and Consultants
- Client contracts, statements of work and invoices.
- Platform statements and payment processor reports, if applicable.
- Bank and payment-wallet statements showing receipts.
- Foreign-currency receipts and the exchange-rate basis used in accounting records.
- Business-expense evidence and a reasonable record of how mixed personal/business costs were allocated.
- Withholding certificates or other evidence where a client deducts tax.
- Records of refunds, chargebacks, unpaid invoices and adjustments.
Do not claim an expense simply because it appears on a bank statement. Keep evidence of what was purchased, why it relates to the business, and whether it is allowable under applicable tax rules. Ensure you aren't missing any valid claims by reading our tax deductions for freelancers guide.
4. Records for Your Wealth Statement
A Wealth Statement should be consistent with the taxpayer’s actual financial position and movements during the year. Keep records supporting opening assets, bank balances, cash, property, investments, vehicles, loans, liabilities, gifts or inheritances where relevant, personal expenses and major acquisitions or disposals. The exact information needed depends on the taxpayer’s facts.
A bank transfer or family payment does not automatically establish the correct tax treatment. Record the nature and source of significant movements and obtain professional advice where classification is unclear. Never invent cash, expenses, assets or liabilities to force an unreconciled amount to zero. To understand common filing errors, read our guide on FBR IRIS Tax Return Problems in 2026.
5. If You Are Registered for Sales Tax
Income-tax records and sales-tax records overlap, but sales-tax compliance has its own requirements. FBR guidance says a registered person should keep records of goods and services supplied, purchased or imported, including descriptions, quantities, values, customer or supplier details and tax amounts where relevant. FBR also identifies invoices, credit/debit notes, bank statements, inventory and utility or employment-related records among supporting records. Check the current Sales Tax Act, rules and FBR guidance for your registration type and transactions.
6. A Simple Monthly Record-Keeping System
- Use a separate business bank account where practical and legally appropriate.
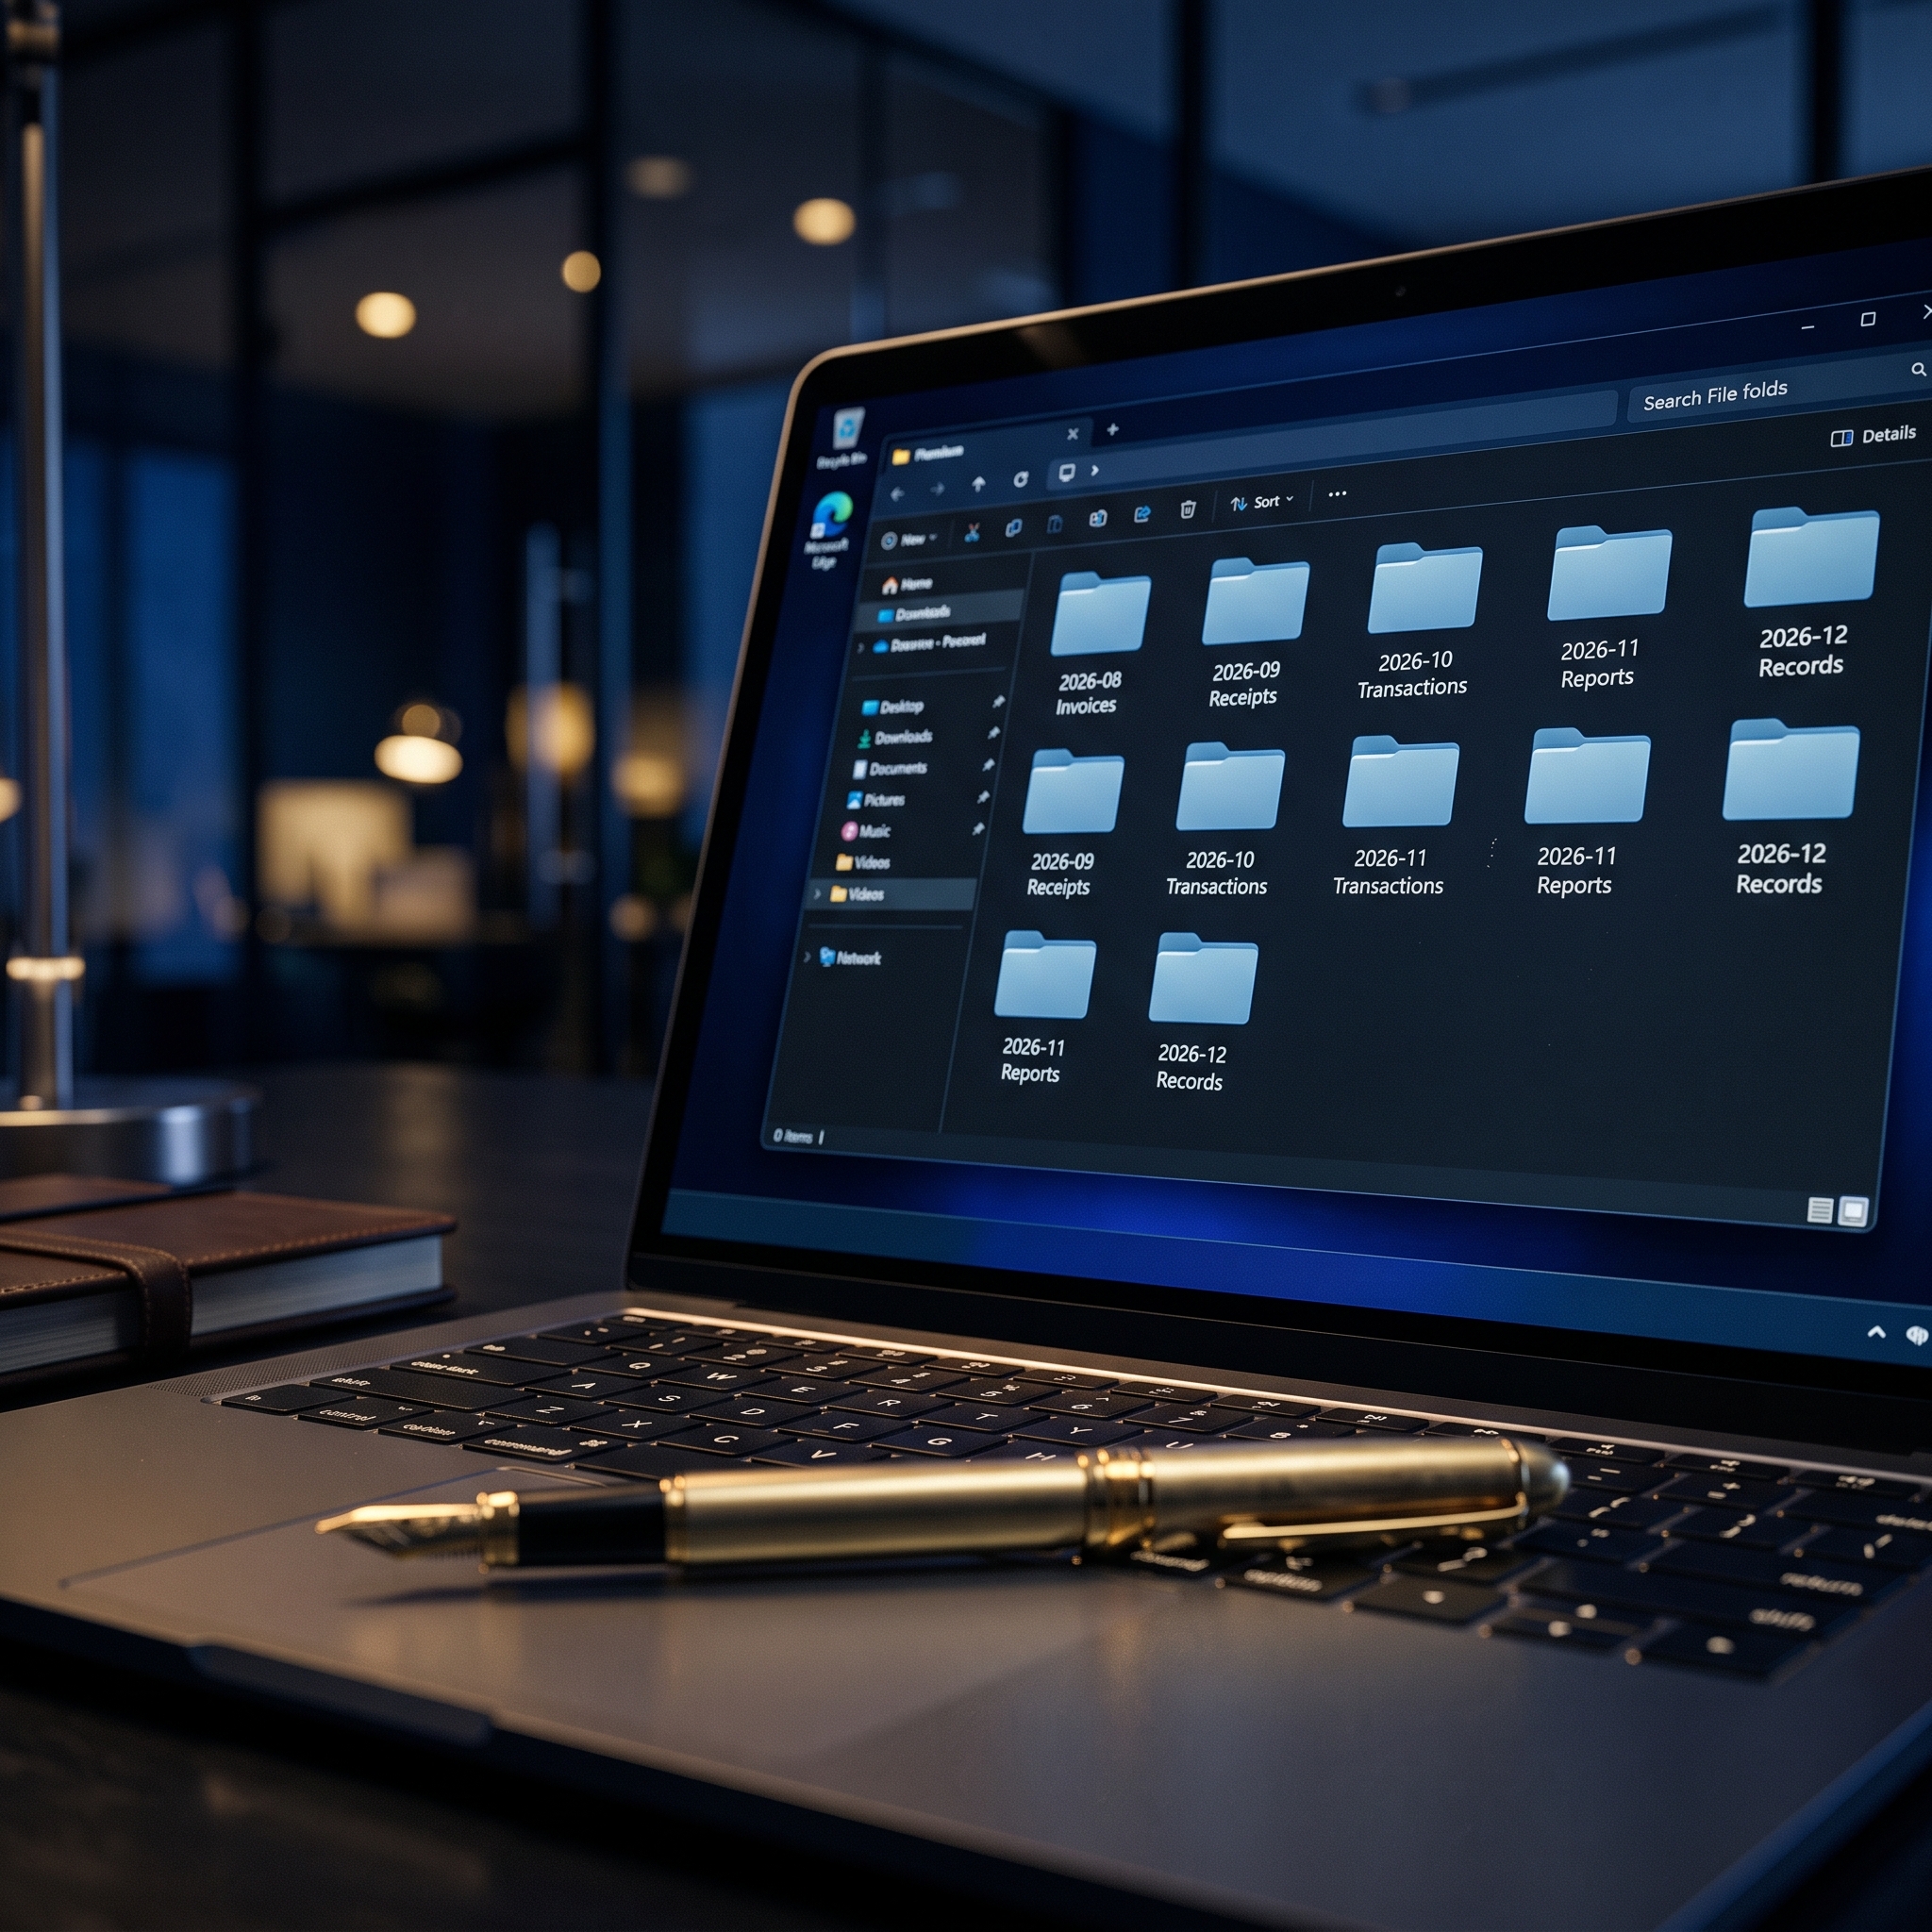
- Store documents in folders by financial/tax year and month.
- Use consistent file names, for example: 2026-08_supplier-invoice_001.pdf.
- Record transactions promptly in accounting software or a controlled spreadsheet.
- Reconcile bank statements to the books every month.
- Match invoices to receipts and payments.
- Reconcile withholding-tax and sales-tax records where applicable.
- Back up records securely and restrict access to sensitive taxpayer data.
- At year-end, reconcile the books to the tax return and Wealth Statement before filing.
For more efficient management, review these tax planning strategies every small business should know.
7. Common Record-Keeping Mistakes
- Keeping only bank statements and discarding invoices or contracts.
- Mixing personal and business transactions without a clear reconciliation.
- Claiming expenses without evidence or without checking tax allowability.
- Failing to retain withholding-tax evidence.
- Using inconsistent sales, purchase and inventory records.
- Saving files only on one phone or laptop without a backup.
- Deleting old records without checking retention obligations or unresolved proceedings.
- Preparing the tax return first and trying to reconstruct the evidence afterward.
8. What If FBR Requests Your Records?
Read the communication carefully and identify the tax year, legal provision, specific records requested and deadline. Collect the relevant source documents and accounting summaries, then check that they agree with the return and statements already filed. Respond through the appropriate official channel and retain proof of submission. If the request relates to an audit, assessment or complex issue, consider professional assistance. Do not ignore the notice or create documents retrospectively that misrepresent the underlying transaction. Learn exactly how to file an income tax return in Pakistan to avoid mistakes.
A tax return is only as reliable as the records behind it. Build the habit monthly: record transactions, reconcile bank activity, and preserve source documents.
Quick Checklist: Are Your Records Ready?
- Filed returns and Wealth Statements saved
- Bank statements downloaded
- Sales and purchase invoices organized
- Business expenses supported by vouchers
- Withholding-tax evidence reconciled
- Assets, loans and liabilities supported
- Sales-tax records and invoices maintained, if registered
- Monthly bank reconciliation completed
- Digital backup tested
- Records for relevant tax years retained and accessible
Want to learn practical income-tax compliance?
Explore MAC Learning Hub’s taxation and accounting programmes to master practical bookkeeping, return preparation, and FBR compliance.
Frequently Asked Questions
How long should I keep income-tax records in Pakistan?
FBR guidance says persons with taxable income should keep income-tax return records for six years. Check the current law and any special circumstances before disposing of records.
What documents should a freelancer keep for tax filing?
Keep client contracts, invoices, platform statements, bank/payment records, business-expense evidence and proof of withholding tax where applicable.
Do small businesses need to keep invoices and receipts?
Invoices, receipts and supporting records are important for substantiating transactions and meeting applicable tax and accounting requirements.
Do I need bank statements if I have accounting software?
Yes. Bank statements are an important independent source for reconciliation and evidence; accounting software does not replace underlying records.
What records should I keep for a Wealth Statement?
Keep evidence supporting assets, liabilities, balances and significant financial movements, including acquisitions, disposals and loans.
How long should sales-tax records be retained?
FBR guidance states that registered persons should retain relevant sales-tax records for six years after the end of the tax period to which they relate.
Can I claim a business expense without a receipt?
Do not assume an expense is allowable without supporting evidence. Keep suitable records and check the relevant tax rules.
What should I do if FBR asks for old records?
Review the notice, requested period and applicable law promptly. Do not ignore it; seek professional advice if the position is unclear.
Disclaimer: This article is for general educational and informational purposes. Tax laws, rates, and procedures can change. The information in this article is based on FBR guidance available at the time of publication and should be rechecked against current FBR requirements before taking a compliance action. It is not a substitute for case-specific tax advice. This article was last updated in November 2026.